AI Is Redrawing the Software Map (Part I): System of Record vs. Replaceable Interface
The debate over whether AI will “kill SaaS” is too simplistic. From where we sit, advising on technology transactions and speaking regularly with strategic buyers, AI is not making software irrelevant. It is changing where defensibility sits and what buyers are willing to pay for.
For years, horizontal software commanded the premium: larger TAMs, cross-industry applicability and platform potential. Vertical software was considered narrower, despite businesses such as Bloomberg, Veeva or Synopsys demonstrating the value of proprietary data, deep workflows and high switching costs.
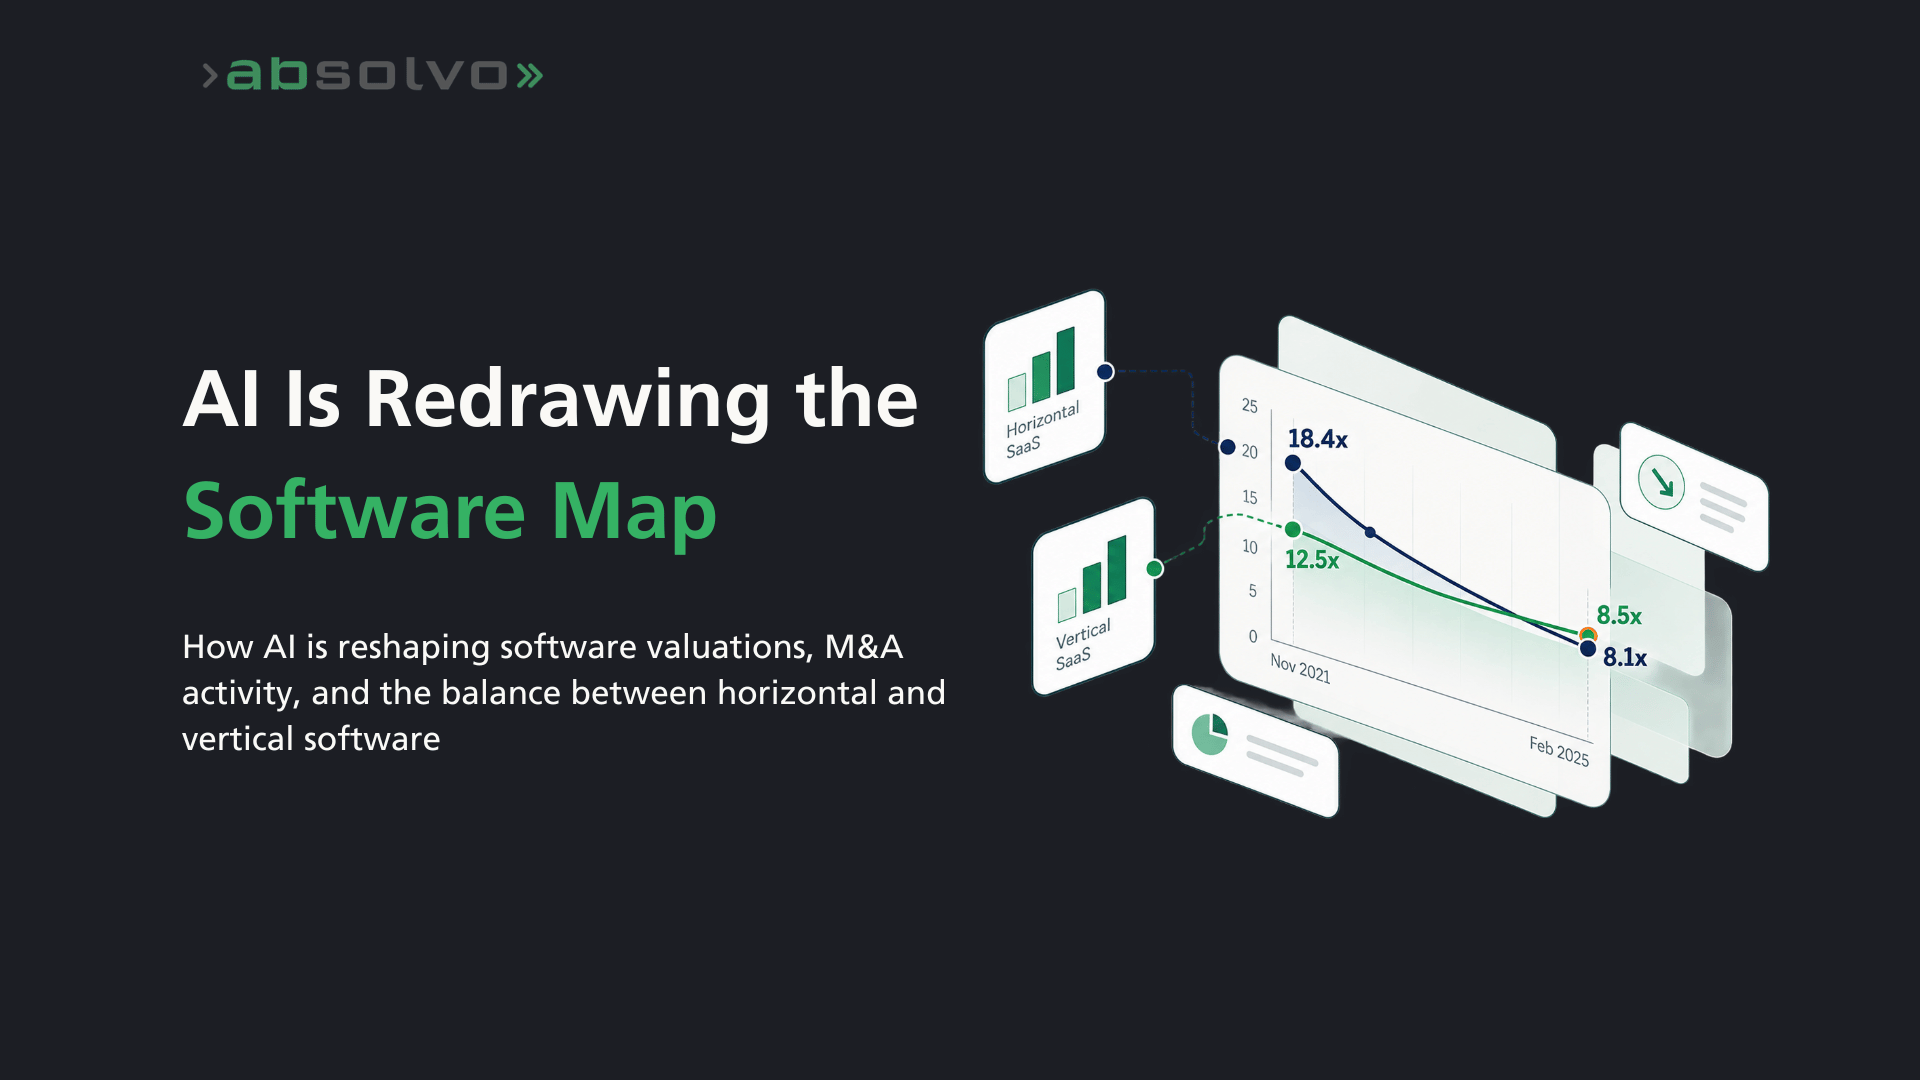
That hierarchy has changed dramatically. According to Blackpeak Capital’s March 2025 SaaS Sector Update, horizontal SaaS traded at 18.4x forward revenue versus 12.5x for vertical SaaS at the November 2021 market peak. By February 2025, the two had converged at 8.1x and 8.5x. Much of the compression reflected higher interest rates and the broader SaaS reset rather than AI alone. But horizontal software fell much harder than vertical peers, ~56% versus ~32%, suggesting that breadth alone was no longer enough to command a premium. This suggests investors were already repricing breadth and paying for depth.
M&A deal mix shows a similar shift: in Q2 2026, vertical software represented 54% of SaaS transactions, up from 46% a year earlier according to Software Equity Group. Buyers increasingly favored specialized workflows, proprietary data and mission-critical functionality.
CEE lacks a comparable dataset, but specialist vertical consolidators are increasingly active in the region, with several international acquirers completing multiple deals across CEE over the past two years. Acquirers such as Everfield, Vesta Software Group, Hawk Infinity, Shop Circle and Valsoft are increasingly active, and we see that interest first-hand: several consolidators approach us directly to discuss opportunities and attend our events to build local relationships.
But systems of record are fighting back
AI initially seemed to reinforce the vertical thesis: generic functionality becomes cheaper to reproduce, while industry-specific data and workflows remain hard to replicate. Yet the first AI-driven software sell-off hit some of the most entrenched systems of record in the market. In early February 2026, a $285bn market rout was triggered by Anthropic's release of enterprise plugins for its Cowork AI agent platform. For instance: Salesforce, ServiceNow, Adobe, and Workday each dropped around 7% in a single day. Investors feared that agents could undermine seat-based pricing and absorb workflows previously monetized by standalone applications.
Since then, that view has become more nuanced. Parts of enterprise software have rebounded as investors started distinguishing between replaceable interfaces and embedded systems of record. ServiceNow's Q2 results showed AI-related annual contract value above $1 billion, subscription revenue up 24% and renewal rates of 98%. Workday rallied on reports that Silver Lake had entered discussions to acquire the company, with Morgan Stanley saying a deal would validate Workday's moat. Salesforce jumped 22% on 27 August after its second-quarter results, its second-best day ever. The move was helped by improving growth and confidence that it can remain a critical data and orchestration layer beneath AI agents. (Not all of the rebound was fundamental: part of it reflected money flowing out of chip stocks back into software stocks.)
The logic is straightforward: an AI agent may become the interface for approving an invoice, generating a forecast or hiring someone, but it still needs trusted data, permissions, integrations, auditability and somewhere to execute the action. A basic CRM or dashboard can increasingly be built in days; years of enterprise data and embedded workflows cannot.
The more useful dividing line is therefore becoming system of record vs. replaceable interface, rather than horizontal vs. vertical.
The same question applies to vertical software
Constellation’s shares fell roughly 50% from their June 2025 peak to late January 2026, as investors grappled with both AI disruption concerns and uncertainty following founder Mark Leonard’s departure. The operating picture has been more nuanced: Q2 2026 revenue grew 17%, but organic growth was only 3%, with acquisitions driving most of the increase. Importantly, management said AI had not yet materially affected revenue growth in either direction, although it was already improving development productivity.
Has the AI-disruption thesis been applied too broadly? A niche vertical ERP deeply embedded in an industry may have more in common with SAP than with a generic point solution. Veeva, for example, rallied in August once the expected AI threat to its niche failed to materialize. But not every vertical app is a system of record, and thin industry tools face the same pressure as horizontal ones.
Conclusion: follow the data and the workflow
The first AI thesis was simple: if software becomes easier to build, software becomes less valuable. The emerging reality is more selective. Products whose moat is mainly the interface or the cost of writing the code are under pressure. Businesses controlling trusted data, critical workflows, permissions and customer relationships may remain highly defensible — whether horizontal or vertical.
So the key question is no longer: horizontal or vertical? It is: system of record or replaceable interface? In practice, that is a spectrum rather than a binary. Put more simply: what has this business built that cannot easily be recreated?
That distinction is increasingly shaping both software valuations and strategic buyer behavior. As Part II explores, it is also reshaping venture funding and raising the bar for M&A.
Absolvo specializes in M&A and growth financing, backed by 180+ completed deals collectively in the CEE region. We support tech companies through strategic exits, private equity transactions, and cross-border growth initiatives. If you are considering an exit or a strategic partnership, our team is ready to help you prepare and position your business toward an exit that could deliver 3-5x its fair value.
Many CEE tech company shareholders may be leaving money on the table as some exits have the potential to reach up to 2-5x fair market value. It’s not a myth; we’ve seen it happen firsthand. A big reason tech exits matter now is that many VCs who invested in 2019-2021 are facing portfolio companies that couldn’t raise a new round in 2023-2024, so the focus is shifting from “raise again” to “exit well.” In a world without free money, premiums aren’t paid for hype, or AI promises alone, especially in CEE where international expansion often delays profitability.
This dynamic is not limited to VC-backed companies. Bootstrapped founders face the same situation, and they are equally positioned to achieve premium outcomes when properly prepared. However, these outcomes are not created at the moment of exit, so founders need to start preparing early, ideally 2-3 years before launching a formal exit process. To completely understand how early preparation drives premium outcomes, we need to step back for a moment – every good story has a beginning.
And in this case, it starts in 2021, a year that felt a bit like the “gold rush” of modern M&A. Capital was cheap, interest rates were near zero, and money moved faster than ever. Ultra-low financing costs and booming equity markets created a perfect storm of aggressive spending and rapid-fire dealmaking, pushing global M&A activity to record highs.
The sobering came quickly. By 2022, global M&A value had dropped roughly 37% year-on-year, a sharp wake-up call for the entire market.
The reasons behind this 37% global M&A value drop hit from every direction:
inflation spiked
interest rates climbed rapidly
financing costs surged
bid-ask spreads widened as tech valuations fell
geopolitical shocks rattled boardrooms
On the deal level, the cracks were just as visible:
PE firms shifted from buying mode to repair mode
several high-priced strategic buyers’ acquisitions from 2020-21 underperformed
write-downs followed
executives behind “big cheques” were put under the spotlight
boards grew cautious on anything not supported by facts and looked like overpaying
The brakes weren’t just tapped – they were slammed. The free-money honeymoon was over, and it hasn’t returned since. Yet the story doesn’t end with a long winter.
Why the Recent M&A Upswing Could Favor CEE Tech Founders
Fast-forward three years, and as we head into 2026, that caution is still present – especially among strategic buyers who remain more selective than their financial counterparts. Still, the ice is undeniably thawing.Forecasts point to a cautiously optimistic rebound in global M&A of roughly 25% year on year, and we feel it too: buyer's appetite is picking up, dialogues are reopening, offers are improving, and momentum is gradually returning.
And when we zoom in on CEE, the picture becomes even more interesting. The talent is world-class – exceptional developers, strong engineering culture, and a vibrant innovation mindset – yet many firms still operate below the scale where valuation formulas turn generous. Years of pouring resources into product and market expansion often mean they haven’t reached the efficiency or size needed to command strong ARR multiples. And while the products themselves are impressive, many CEE tech companies struggle to fully unlock their commercial potential.
This is where the idea of a “tech exit” steps into the story. Not every company can be a market leader, and not every business reaches the level of profitability or economies of scale that trigger automatic premium valuation. In many cases, you’re not selling “amazing EBITDA” today, but the proven fundamentals and credible path to reach it. Yet CEE founders – with their talent, resilience and engineering excellence – deserve outcomes that rival those in more mature markets. To get there, however, they often need to follow a different path.
And that path does not begin when founders feel tired and decide they finally want to sell. At that point, it’s usually too late. The companies that secure the strongest valuations are the ones that start preparing long before a process officially begins – ideally 2-3 years earlier.
But how do you convince the same strategic decision-makers who got burned by overpaying 4-5 years ago to still pay a 2-3-5x premium above fair value today? Early positioning, disciplined financials, and validated synergies are among the foundational pieces that unlock premium offers. They are the difference between an average deal and a standout result in today’s CEE investment environment.
The 8 Exit Readiness Factors That Separate Breakout Deals from Average Ones
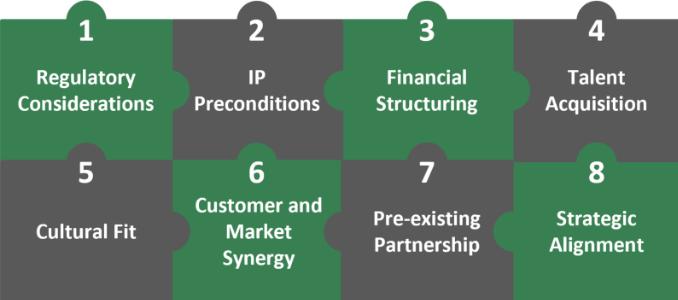
So, what does “real preparation” actually look like? We’ve distilled it into 8 critical factors that repeatedly decide whether a company lands at fair value or earns a premium. In practice, that premium isn’t negotiated with the buyer company, but with the people inside it, each with their own motivations and priorities. Want to learn what those stakeholders care about and how to navigate them? Read more here:
Regulatory considerations: Preparing for FDI approvals and competition scrutiny is key, especially as engaging with strategic buyers early can expose sensitive information if not carefully managed but also may have impact on timing (can cause months of delay).
IP preconditions: Clean, defensible and transferable IP in every tech deal is critical, particularly in high-barrier or fast-evolving markets where buyers place a premium on protected innovation.
Financial structuring: Further financial deal terms matter as much as headline price, and many M&A deals include a purchase price adjustment mechanism, earn-out component or other solutions to gap valuation debates. Also, you need to decide in advance if you’re optimizing revenue growth or EBITDA.
Stable team and contracts: A committed team with limited key-person risk and strong contractual foundations help ensure continuity and reduce post-transaction uncertainty.
Cultural fit: Cultural alignment remains a key success factor, with 95% of executives considering it critical for smooth integration. For the founders and management this is also key: its about deciding where you and your team will belong the day after closing.
Customer and market synergy: Clear upside potential through cross-sell; upsell and strong retention metrics can significantly enhance perceived value. Strong synergies can take the deal into different horizons.
Pre-existing partnerships: “Try-before-you-buy” M&A, where partnerships and integrations set the stage for acquisition, paving the way for a breakout tech exit.
Strategic alignment: Buyers are driven by different priorities, from market expansion to capability acquisition, so alignment across product, technology and strategy is essential.
If this topic has sparked your interest, you can explore deeper insights in the downloadable content on the right. Created by Absolvo’s experts, the material is designed specifically for tech founders preparing for a breakout exit.
In this article we have analysed a thorough combination of
qualitative data from Absolvo’s own discussions with major global and regional strategic buyers and private equity funds (as part of our regular calls with them), including investors from the US, Europe or even from Singapore,
latest market data and macro trends translated to the CEE tech ecosystem
With these global trend analysis and real buyer quotes we aim to paint a picture of what founders and VCs should expect going into 2026.
What we can conclude: though uncertainty is not disappearing, stabilising macro indicators, renewed buyer appetite, and a significant amount of dry powder position 2026 as one of the strongest exit years of the decade. All these paired with resilient tech valuations and growing investor interest in Central and Eastern Europe, our 2026 CEE Tech M&A Outlook points to a turning point where both strategic and PE investors will be ready to buy: strategics will pursue assets with clear strategic fit, while Private Equity will focus on targets that qualify as a platform or unlock add-on consolidation opportunities within their thesis.
However, they don’t chase hype (therefore are cautiously analysing the real value behind AI or other similarly favoured industries) and some of them have just recently discovered the potential in the CEE tech landscape. In the second half of the article we have even collected some hands-on advice for both founders or VC fund managers that are planning an exit for the next 6-18 months.
1. Uncertainty is here to stay
Over the past three years, the M&A market faced a perfect storm: inflation spikes, interest rate uncertainty, volatile valuations, and geopolitical noise (war in Ukraine, tariff wars, political turbulence, etc.). This was no different in H1 2025: global M&A volume was 9% lower YoY, but value rose by 15% YoY, reflecting a shift toward megadeals, meaning the market remained selective, with investors concentrating capital into fewer, high-conviction transactions rather than spreading risk across smaller deals.
If you have been part of a transaction in the past 24 months, you certainly experienced that deal-making is slower, due diligence is more thorough, which has slowed processes but increased seriousness and quality of intent. Also, cautious buyers rarely pay a premium without real fundamentals and strong reasoning. In a recalibrated market, valuation discipline dominates: global median M&A EV/EBITDA multiples stood at ~9.3x in mid-2025 as of June 2025, while European PE deals averaged ~11.2x, compared to ~8.5x for corporate buyers.
Macro conditions seem to stabilize inflation and base rates have normalised, financing is more predictable, but what we have had to learn since 2021 is to expect that there will be something unexpected in the macroeconomic trends, which means this has to be part of our strategy (both on the sell- and the buy-side). In other words: "uncertainty is no more a bug, it is a feature”.
2. Dry powder needs to be deployed, investors’ appetite needs to be fed
With global PE dry powder estimated at over USD 2.5 trillion, capital sitting idle is no longer neutral. Uninvested capital creates opportunity cost, IRR pressure and growing LP expectations - all of which translate into increased deal appetite, even in a selective environment. Many investors, especially in the US paused or reconsidered deals in early 2025, but these will be missing from product portfolios, books and revenues and strategies in general.
In practice, this means that while buyers remain cautious, they cannot stay on the sidelines indefinitely. Capital needs to be deployed - and hungry investors need to be fed. Deloitte’s most recent M&A outlook shows that around 90% of PE dealmakers expect M&A activity to increase over the next 12 months, with a similar majority anticipating higher deal values. Confidence is returning - cautiously, but decisively.
In uncertain times, buyers are very selective - but to be honest, good and successful investors have always been so. Companies with healthy strategic and financial fundamentals and strong future potential keep being acquired and sold. Strategic buyers primarily look at potential strategic fit – we will explore this in more detail later. On the other hand, a typical PE is first looking at metrics like topline growth, retention, LTV/CAC, etc. For them, a deep insight into company metrics is a MUST. Apart from metrics, there has to be a clear technological advantage and/or a focus on a niche segment. As one major global PE investment firm told Absolvo “We prefer tech-led advantage and need to see a clear differentiator in every case we seriously investigate”.
3. Tech M&A: Outperforming the market
The technology sector continues to be among the most attractive sectors for M&A activity, both in Europe and globally: Tech M&A in 2024 ended the year strong, well outpacing the overall M&A market’s 10% growth in 2024 with 32% growth in deal values.
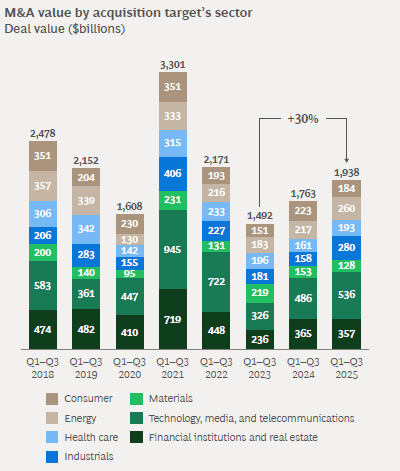
According to BCG’s M&A Report of the first 9 months of 2025 overall global M&A activity experienced a 10% YoY growth, with the TMT sector leading in deal volume ($536 billion). If we look at valuations, one study shows that the IT sector clearly outperforms the market with an average of 13,2x EV/EBITDA multiple (vs. 9,3x across all sectors).
Boston Consulting Group. (2025). The 2025 M&A report.
In 2026 tech remains attractive among Private Equity firms, too, it is the No 2. domain for PE investors following life sciences and health care. 74% of survey participants for Mergermarket expect to invest in technology, which is the second most popular industry after life sciences (including healthcare).
Dechert LLP & Mergermarket. (2025). Signs of a Gradual Thaw: 2026 Global Private Equity Outlook.
Within niche tech segments, cybersecurity, vertical SaaS, AI-enablement and data infrastructure continue to attract disproportionate interest. In Europe, mega-deals have driven much of the recent growth - proof that strategics and PEs are ready to bet big again. 2025 has seen $1B+ cybersecurity roll-ups and vertical SaaS/IT services mergers in Europe, with CEE also part of the wave as SaaS M&A activity surged 28% YoY, on pace to become the most active year ever.
Dechert LLP & Mergermarket. (2025). Signs of a Gradual Thaw: 2026 Global Private Equity Outlook.
However, in case the motivation is not purely based on missing pieces of the product portfolio, investors are in love with the sticky, ‘boring-but-beautiful’ software categories (ERP, HR, payroll, invoicing, inventory management, etc.). An emerging group of investors, the so-called software consolidators’ follow a special buy-build-hold philosophy, reinvesting in operations and bolt-ons to drive long-term value rather than exit timing.
Therefore they typically acquire companies with sticky mission-critical software, high retention and strong lifetime value - assets where users are reluctant to churn and where future cash flows are more predictable and defendable. Global and regional consolidators such as Jonas Software and Vesta Software Group are already actively investing in CEE, closing transactions, while some others like Shop Circle or the Publix Group have recently put this part of Europe on their potential target list, but certainly more activity can be expected from this segment.
AI is hot, but both strategics and PE investors filter out AI “storytelling” and overclaiming. During our end-of-year discussions, investors confirmed to the Absolvo team that they are only interested in companies that have built and shipped real AI projects, with evidence of customer adoption and satisfaction. Especially those coming from the tech sector themselves, have been part of AI-related developments. As a strategic investor in ERP systems put it: “we see AI as evolution, not revolution”
At the same time, regulatory frameworks such as the EU AI Act, DMA and DSA are increasing scrutiny during due diligence. IP ownership, data governance, cybersecurity and compliance readiness have become core diligence topics, reinforcing the need for substance over hype.
In many cases AI investments are still driven by the FOMO affect, with nice engagement metrics, but unproven business models. Therefore, it is not for everyone. The above mentioned vertical software integrators have a specific view: as they are primarily looking for predictable recurring revenues, EBITDA-positive and preferably local / regional market leaders, they rarely engage with purely AI-driven businesses and will wait out until this niche is ready for consolidation.
However, AI is becoming a horizontal aspect of investments, too. Talking with global leading European PE firms like Permira or EQT, they all emphasized that in B2B software, “no AI thesis = no deal” is becoming the norm. As one of them put: “…anything we consider nowadays, there has to be an AI thesis around that”
4. CEE is an underexplored but increasingly attractive opportunity
Regarding tech deals, Central and Eastern Europe is playing its own role: as we have experienced in other parts of the world, the sector witnessed high-value deals in Q4 2024, led by strategic buyers focusing on digital growth, altogether there was a decline in deal volume, but a substantial increase (424%!!!) in value. Apart from the mega deals, mainly add-on acquisitions dominate. This is classic PE behaviour: using strong regional engineering talent and attractive price points to fuel platform growth.
For many funds and strategics, CEE is turning into an underexplored opportunity rather than a “nice-to-have.” Some global strategic acquirers have repeatedly admitted to Absolvo that they historically overlooked the region - but rising valuations in Western Europe and the US are pushing them to broaden their horizon. “We know little about CEE, but we have recently turned toward the region.” said an M&A director of a major European B2B software developer company specialising in ERP, accounting and business management solutions.
If we look at specific verticals and buyers in niche segments like Palo Alto Networks or Encora in cyber security, their primary geo focus is elsewhere, mainly US and Western Europe. But if a certain technology fits their portfolio, let alone it is the missing piece or there is an interesting innovative element, they can be a relevant target. CEE is often perceived as a region of outstanding engineering and strong technology foundations - a compelling starting point, but rarely a deal thesis on its own.
The winning narrative builds on that base with a scalable product, proven execution, and/or a platform opportunity in a fragmented market, where consolidation is structurally embedded for companies that are born regional - or ideally born global.
5. How to prepare for 2026 (and beyond)
High importance on being strategic fit
During our end-of-the-year discussion with appr. 50 strategic investors and Private Equity firms, one of the key points were to identify how they look at a potential opportunity. What has been undoubtedly common in all strategic buyer talks was – no surprise - that strategic match is THE key!!!
This means business (sales, marketing) and product strategy alignment between buyers and sellers. Acquirers can have multiple motivations, from market expansion goals through diversification to cost savings - understanding this and clearly demonstrating how a target can accelerate those objectives is often one of the most decisive value drivers - in such cases, buyers are willing to pay even 2-3 times above fair market value.
Additionally, if a product can scale independently or integrate seamlessly into the acquirer’s portfolio, that flexibility means strategic value and opens up various post-acquisition scenarios. For exceptional CEE tech companies with great products and solutions, a larger strategic player with existing regional or global sales-marketing channels can be a real upside, opening endless opportunities.
As one M&A director put it:
“When strategic fit is clear and the product or talent is globally competitive, valuation becomes secondary - and geography irrelevant.”
In another discussions similarly, the hierarchy of criteria was revealed: Strategic synergies first; then strong management, good client base, scalability of the product / service – and valuation last.
Private Equity funds remain bullish - 2026 could be the breakout
Several major PE investors confirmed strong activity in 2025 and rising expectations for 2026. PE is gearing up for significant dealmaking - and CEE is more often on the consideration list. However, strong metrics and transparency are non-negotiable. For platform investments retention, gross margin, LTV/CAC, 30%+ growth - these are now the first filter, not the last. Regional VCs like Genesis, CEECat and European/global players like Hg Capital or Permira all emphasized the importance of strong marketing and go-to-market execution capabilities – a feature that is one of the key challenges of CEE-rooted scaleups.
For those planning an exit - or aiming to continue growing as a regional champion, potentially through inorganic expansion - 2026 may offer a particularly attractive window for transactions. Improving market conditions, active buyers and growing deployment pressure are creating promising opportunities. Regional VCs should evaluate their portfolios now: Which companies are strategically attractive? How prepared are their portfolio companies for a potential acquisition? Is exit preparation part of the overall strategy and is it in line with further product development plans? Optimization and preparation takes time, often 2-3 years, so it has to be started ASAP.
For those companies, where a transaction is still further out, this period provides valuable time to prepare. Exit readiness is rarely a short process; it often takes two to three years. Understanding your buyer universe within your sector, identifying potential strategic synergies, and embedding these insights into your long-term strategy can bring 2-3-5x of fair market value when the window opens.
All in all, if you plan a transaction in the next 2-3 years, you need to prepare ASAP. If you are interested in:
how prepared you are for a strategic exit or a PE transaction?
what are the fair multiples in your market?
and how preparation can help you increase a potential exit value?
Feel free to reach out to the Absolvo Team for a consultation. We wish you clarity, discipline and momentum in the year ahead!
The analysis combines qualitative data coming from investor interviews conducted by Absolvo and industry benchmarks plus market data from sources including (but not limited to) PitchBook, Mergermarket, Sifted, Goldman Sachs, EY, Bain&Company, Deloitte and PwC.
Software consolidators that have been active across North America and Western Europe are increasingly turning their focus to CEE region. As Absolvo successfully closed deals with them (and negotiating more continuously), we see growing interest from leading global and European software consolidators – including Jonas Software, Everfield, saas.group Visma, Vesta Software Group, Abingdon, Valsoft, Shop Circle, Balio and others – actively targeting Europe as well as the CEE and SEE markets. We maintain ongoing dialogue with these buyers, exploring new opportunities in the region’s fast-maturing software ecosystem.
What Defines a Software Consolidator
Software consolidators differ fundamentally from traditional private equity (PE) firms or strategic buyers. They operate under a Buy, Build & Hold philosophy, i.e. acquiring, and developing vertical software and SaaS companies to create sustainable long-term value rather than short-term financial returns.
Their focus areas include:
ARR stability and recurring revenues. They target companies with predictable cashflows, high retention, and strong customer lifetime value. Low churn is key! Check your industry average, should you be better than the others, that can be valuable.
Founder-friendly approach that offers flexible transition plans, keeping management teams in place, and ensuring cultural continuity.
Operational efficiency, centralising finance, HR, and IT; leveraging cross-portfolio synergies; and driving scalability across fragmented markets. Because they are usually backed by permanent capital (in some cases publicly listed companies), consolidators can hold assets indefinitely, prioritising operational excellence and organic growth over time
How Consolidators Differ from PE and Strategic Buyers
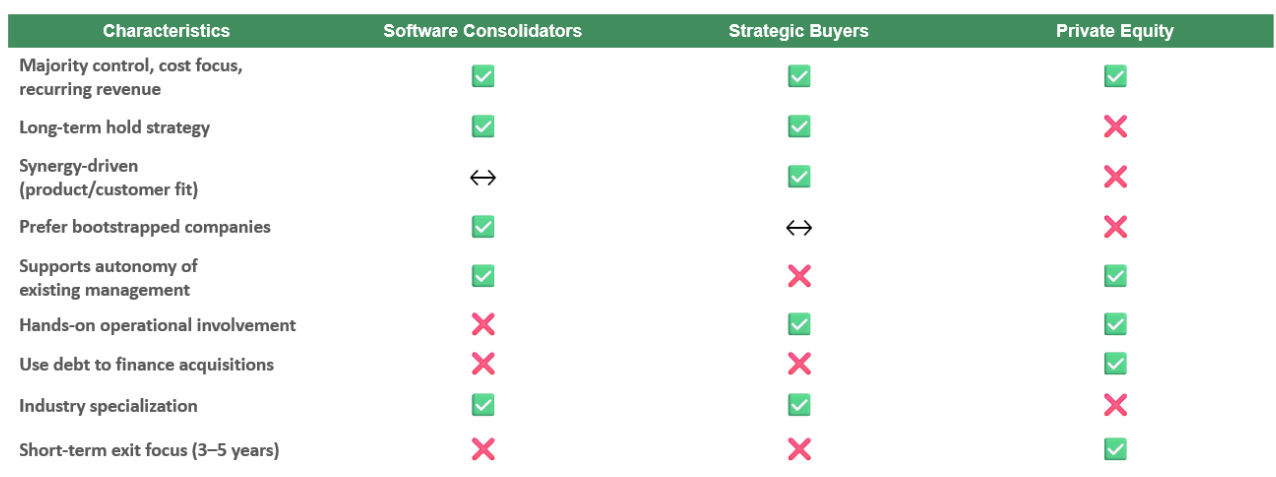
Founders or VCs considering an exit should understand the three key buyer types in SaaS M&A:
Private Equity (PE): financial investors aiming for leveraged growth and a 3–5-year exit horizon.
Strategic Buyers: larger software or IT groups acquiring for technology or customer synergies, often integrating targets into existing structures.
Software Consolidators: permanent owners who combine the operational discipline of strategics with the agility and speed of financial investors. They offer continuity, stability and partnership for founders.
Tailoring your transaction story and financial narrative to these buyer profiles is critical to maximising value and closing a deal that aligns with your goals.
Comparing Software Consolidators with Strategic Buyers and Private Equity
Ideal Targets for Software Consolidators
From Absolvo’s transaction experience, several attributes define the “sweet spot” for consolidators when evaluating acquisition targets in Europe and CEE / SEE:
Predictable recurring revenues: consolidators favour SaaS or software-license models with high retention rates and typically €2-10 million ARR size (some might pursue larger deals), or from 500k-1million EBITDA
Vertical or niche market leadership. Companies serving a well-defined vertical segment – with strong product-market fit, established brand reputation and defensible customer relationships – are preferred over generalist or horizontal platforms. However, they are such serial acquirers who rather look for min 15-20% ARR growth and horizontal, global solutions. Meaning should you be a rather local or regional software business, or a SaaS company with customers all around the world, these investors can be equally an option too.
Most consolidators seek EBITDA-positive businesses, valuing stable cashflows over hyper-growth, while part of them are not keen on short term EBITDA but ARR growth.
Strong teams and founder continuity: transactions often allow founders or key managers to leave (even immediately) or remain involved post-deal. Leadership continuity and a collaborative mindset are viewed as core to integration success.
Why Europe and the CEE Region Are in Focus
The consolidation trend is no longer confined to Western Europe. In recent years, we see CEE and SEE emerging as strategic growth regions for global consolidators.
Absolvo’s experience highlights three drivers:
Attractive valuations: CEE SaaS firms often trade below Western European multiples despite strong retention and solid ARR.
Fragmented market structure: ideal for roll-ups and operational integration.
Proven founder quality: the region has a deep pool of experienced founders who have built profitable, global-focused / export-ready SaaS companies
Recent regional examples include Smartbill’s acquisition by Visma or Vesta Software Group’s acquisition of ArenimTel – that was solely advised by Absolvo. These transactions illustrate the sweet spot for consolidators: stable, recurring-revenue businesses with loyal customer bases and vertical expertise.
AI Integration and Its Growing Role in SaaS M&A
The impact of AI on software transactions is increasingly visible. Consolidators now assess how AI enhances a target’s efficiency, product roadmap, or data strategy. For founders preparing to sell, articulating a credible AI vision can significantly boost buyer interest and valuation.
Transaction Dynamics and Valuation Insights
Software consolidators maintain dedicated in-house M&A teams, allowing them to evaluate opportunities efficiently and move swiftly once interest is established. They avoid bidding wars but are willing to pay competitive valuations for high-quality assets with transparent metrics and recurring revenue visibility.
Based on our experience, they are quick in assessing the targets, able to provide an LOI in 2-3 weeks. The chance of closing a deal is extremely high, they understand what they want and once Parties find common ground, they move quickly – that is highly preferred by the CEE entrepreneurs also.
Founders with a clear, well-structured transaction story, clean financial data, and defensible ARR metrics tend to achieve stronger outcomes, even within consolidators’ disciplined valuation frameworks.
The vertical software integrators prefer all cash deals, which may not be the case when it comes to mid-market strategic buyers (where founders may get stocks). Therefore, these software buyers can be a good option for VC-backed tech companies also.
Absolvo’s Role in the CEE/SEE SaaS M&A Ecosystem
Through our direct relationships with leading consolidators across Europe and beyond, we help founders:
Understand buyer logic and value drivers
Prepare financials and KPIs that resonate with investors
Communicate growth, scalability effectively
Navigate deal structures that result in better deal outcomes
Our ongoing conversations with over 160 investors monthly (including top consolidators) and our successfully closed deals with Vertical Software Integrators ensure that Absolvo’s clients in Hungary, Romania, Slovakia and the wider CEE/SEE region remain visible to the most active and relevant acquirers in today’s market.
How Private Equity is Evolving in Central and Eastern Europe
Private equity activity in Central and Eastern Europe continues to reflect the region’s growing maturity and strategic importance. As investors increasingly recognize CEE’s strong fundamentals and integration into global markets, deal flow and capital commitments have remained resilient.
Global private equity investment reached approximately €755B in H1 2025, with Europe accounting for around one quarter of this total (€220B), while the CEE region represented about €12B.
Several international private equity firms are highly active in the CEE region like Cinven, Hg or Ardian Group, and regional private equity firms like Abris Capital, Innova Capital or MCI Capital are also building platforms and consolidating. This continued presence of leading firms underscores the long-term strategic commitment to the region.
There are several trends influencing the world of PE. Globally, AI and advanced analytics are starting to reshape how investors screen and manage companies. In CEE, however, adoption is still at an early stage and largely limited to pilot projects. At the same time, valuation levels in CEE have been gradually moving closer to Western Europe, reflecting rising investor appetite and greater market maturity. In this environment it is worth turning to the basics - what private equity means, how it works in CEE, and how it differs from other forms of investment.
What is Private Equity?
Private Equity (PE) refers to direct investments into private companies, or public companies taken private, with the goal of enhancing value through active ownership and operational improvements. Unlike passive shareholders, PE investors actively shape strategy, strengthen management, and drive growth initiatives. The eventual goal is to exit the company at a profit, usually within a defined time horizon. Private Equity firms generally aim for a 2-3x return on their investment over a 4–7 year holding period. According to Invest Europe and Pitchbook data, European mid-market funds have delivered around 17% net IRR over a 10-year horizon. These figures illustrate the return profile investors expect, though actual outcomes vary by strategy and region.
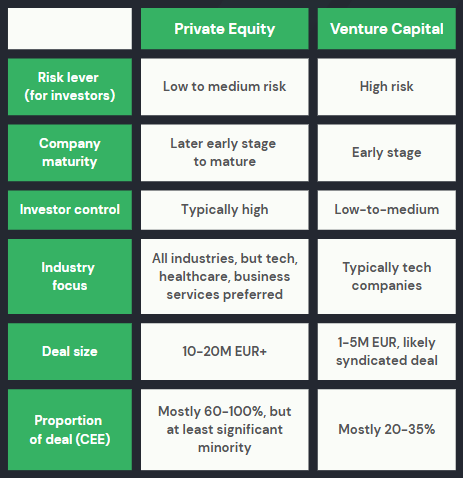
Many times, you’ll hear “PE vs VC”, but to be precise on it: "Private Equity" is the broader umbrella term for investing in private companies. "Venture Capital" is one specific, distinct category under that umbrella, distinguished by its focus on early-stage companies with high growth potential Other PE strategies - such as growth, buyout, or turnaround - target more mature businesses that already generate revenue and profits. PE investments are larger, the risk profile is lower, but the expectations for discipline and results are higher. Private equity is commonly used to describe larger buyout and growth funds.
Comparing Private Equity and Venture Capital in CEE (based on Dealroom and Absolvo deal experience)
The Evolution of Private Equity in Europe
According to Invest Europe’s European Private Equity & Venture Capital Activity Report, total investment value across Europe reached around €126B in 2024 and €220B in 2025 H1, marking a strong rebound from prior years.
Key highlights reflected in the data:
Since the early 2000s, both the number of PE/VC firms and the volume of deal activity in Europe have grown substantially, despite cyclical downturns.
While overall deal volume has declined in recent years, the average deal size has increased sharply.
Buyouts continue to represent the majority of total value, confirming their role as the dominant driver of private equity activity.
Central and Eastern Europe specifically shows investments of €2.83B - up 50% year-over-year - with buyouts alone accounting for nearly €2B.
Annual investment value in the CEE region
Structures and Types of Private Equity Deals
Not all PE deals look the same. Founders may encounter different structures depending on their stage and objectives:
Growth capital: PE funds provide a minority stake to finance expansion, whether into new markets, acquisitions, or new product development. This is common in CEE when a successful domestic business seeks to scale across the region. Deal sizes typically start from around €5-10 million in CEE, with larger transactions reaching €30-50 million, depending on the sector and maturity of the company.
Buyouts: Here, the PE investor acquires a majority stake, often in situations where founders (or other financial investors) want to partially cash out, or where succession is an issue in family-owned businesses. Management buyouts (MBOs) are also common, PEs really open to finance talented management to takeover businesses and take it to a next level.
Mixed deals: A combination of growth capital and buyout, where both expansion and partial exit are on the table.
Beyond providing capital, PE funds apply distinct strategies to create value. These approaches vary from growth support to restructuring, and from management-driven buyouts to complex leveraged transactions.
Private Equity Strategies
Private equity funds deploy a variety of strategies to generate returns and create long-term value. These approaches differ by deal structure, ownership level, and the operational levers applied to portfolio companies. As a company owner interested to engage private equity, you must know this list:
1. Buy & Build
PE firms often acquire a platform company and then make multiple add-on acquisitions to create scale, synergies, and market dominance. This allows faster growth than organic expansion, creates economies of scale, broadens service offerings, and increases valuation multiples. Some PE firms in our region executed 20-22 add-on acquisitions per year. In CEE, buy & build is especially relevant in these fragmented markets, where PE funds often back management teams to lead consolidation and create regional champions.
Higher exit multiple due to increased size and market share
2. Management Buyout (MBO)
PE investors support the existing management team to acquire a controlling stake in the company, often as part of succession in family-owned businesses. While in Western Europe managers are expected to co-invest significant personal capital, in CEE this is rarely realistic, so investors use flexible structures to ensure alignment.
How does it add value?
Ensures continuity and incentivises management
Vendor financing or deferred consideration
Sweet equity structures tied to performance
Management incentive plans linked to value creation
3. Leveraged Buyout (LBO)
An LBO uses debt financing to acquire a company, with the target’s cash flows servicing the debt. This structure requires mature, cash-generating businesses, and in CEE, financing depends heavily on local banks’ willingness to support M&A.
Strategic repositioning to increase valuation multiples
4. Growth Equity
Minority or majority investments into companies with proven models and predictable cash flow. Unlike VC’s high-risk bets, PE funds can be comfortable with steady growth of 10–20% annually. In CEE, even in growth deals, funds often prefer significant minority or majority stakes.
How does it add value?
Capital injection for expansion (new markets, acquisitions, product lines)
Professionalisation of governance and operations
Strengthening management with key hires
Driving digital transformation
5. Turnaround / Restructuring
Targeting distressed or underperforming businesses, this strategy focuses on stabilisation and recovery. Investors intervene with operational, financial, and governance improvements to restore profitability.
How does it add value?
Cost restructuring and operational efficiency
Debt renegotiation and balance sheet repair
Supply chain optimisation and management changes
Strategic refocus on core profitable segments
6. Carve-Outs
PE funds acquire non-core divisions from large corporates and transform them into independent businesses. This requires setting up standalone structures and focused management teams.
How does it add value?
Unlock hidden value by focusing on core activities
Dedicated management and independent strategy
Efficiency gains and growth potential as a standalone entity
7. Secondary Buyouts
One PE fund sells a portfolio company to another PE fund, often as part of the next growth phase. This is increasingly common in CEE as the ecosystem matures.
How does it add value?
Continued scaling or international expansion
Fresh operational improvements
Optimisation of exit timing for sellers and new growth for buyers
Main takeaways for founders interested in Private Equity deals
Private equity in Central and Eastern Europe is a powerful force shaping ownership transitions, regional expansion, and long-term value creation. With rising valuations, more sophisticated deal structures, and growing investor appetite, CEE aims to align more closely with Western European markets while still offering unique opportunities. For founders and management teams, success in this evolving landscape will depend on readiness: strengthening governance, embracing technology, and engaging with the right partners to unlock growth and liquidity.
Why Absolvo?
At Absolvo, we prepare businesses and their owners, management for an exceptional PE deal, working with private equity investors across CEE and Europe, combining local insight with international transaction experience. With 380+ completed deals, we know how to position companies for the right investors, negotiate effectively, and maximise value at exit. If you are considering private equity as a path forward, our team is ready to guide you every step of the way.
H1 2025 saw a 9% global drop in deal volumes, even as deal values surged by 15%, driven by bigger, high-conviction transactions. Europe, however, is challenging that global trend – based on Pitchbook data:
10,274 M&A deals totalling over $516 billion were completed—marking the highest deal count in more than a decade.
Q2 alone saw $256.3 billion in deal value and 5,205 transactions, underlining sustained momentum.
Meanwhile, Pitchbook also reported that Europe led the globe in private equity exits during H1 2025, surpassing North America in deal count.
Surging appetites (European M&A) in H1 2025, according to Pitchbook data
What is driving deal activity in Europe?
Several factors explain Europe’s resilience in H1 2025 and support a positive outlook for H2:
Valuation gap vs. US.: European companies are still priced lower than US peers, which draw interest from strategic and PE buyers.
Financing advantage: The ECB cut rates twice this year, while the US Federal Reserve kept steady. Lower financing costs support both dealmaking and valuations.
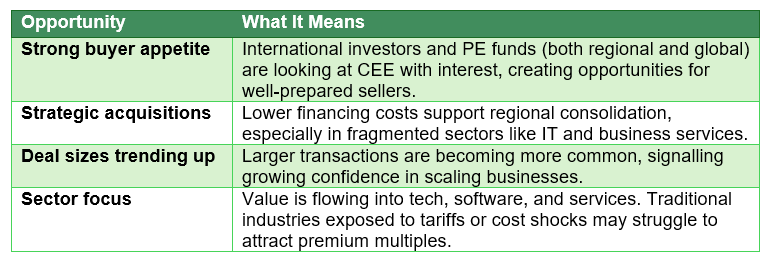
Sector focus: Tech, IT services, and software continue to attract the most activity, while energy, automotive, and chemicals remain under pressure from tariffs and higher input costs.
Sustained appetite from non-European acquirers: PitchBook data shows that despite softer volumes in recent years (compared to a big boom in 2021-22), overseas buyers continue to deploy significant capital into European targets, with $114.9B already recorded in 2025.
European M&A activity with non-European acquirer (2015-2025)
Snapshot of CEE: Strategic opportunity and confidence
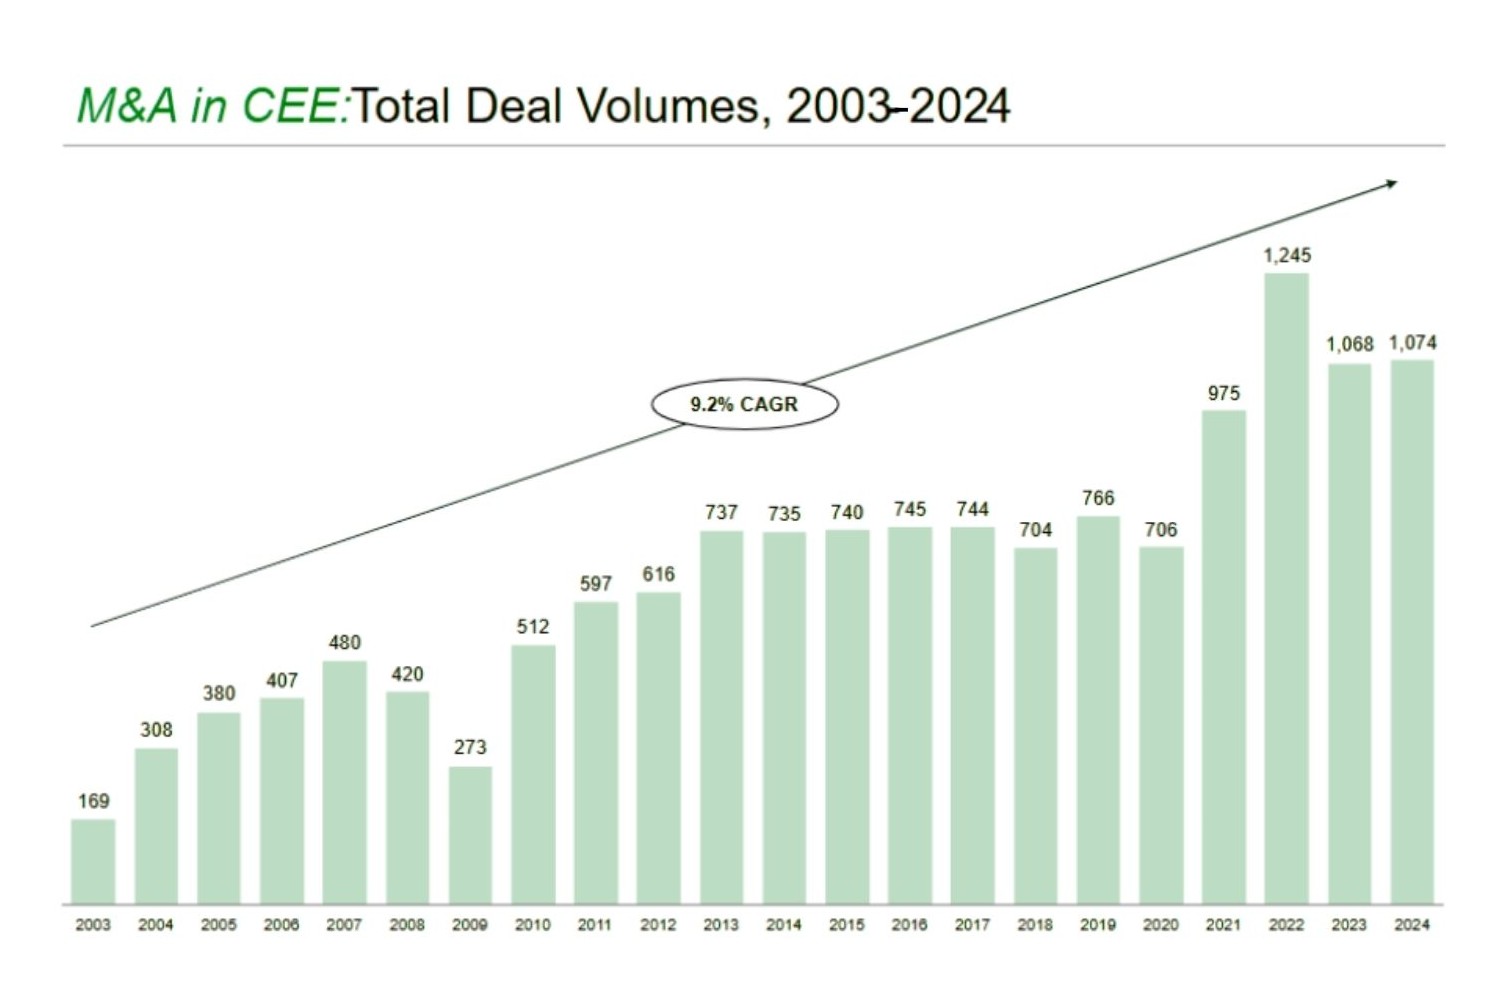
Looking back to the M&A history of the region, MergerMarket analysis shows a strong upward trend in deal volumes across the CEE region since 2003, growing from 169 deals in 2003 to 1,074 in 2024. It represents a 9.2% compound annual growth rate (CAGR). After a peak in 2021 (1,245 deals), volumes slightly declined but have stabilized above 1,000 deals annually in the past three years, signalling sustained transactional activity in the region that seems to be progressing in 2025.
M&A in CEE: Total Deal Volumes (2003-2024)
Coming back to 2025, CEE continued to remain stable on sell-side activities, while buy-side transactions went up 3% in the beginning of 2025, according to Dealsuite. In comparison, the UK & Ireland (+8%) and the Netherlands (+6%) saw stronger buy-side momentum, while DACH (–3%) and France (–6%) experienced declines.
H1 2025 already saw notable CEE tech transactions, such as the acquisition of Poland’s Dealavo. EY also reported that while deal count in the region slowed, deal values jumped by 113% YoY, with mid- to large-scale tech transactions doubling. This shows CEE is no longer just a talent hub – it’s delivering real exit opportunities.
Across these deals, three patterns stand out:
Exit timing: founders sold after proving €10–20M ARR, before heavy international expansion costs kicked in.
Strategic logic: Western buyers used CEE acquisitions to add tech modules or engineering capacity faster and cheaper than building in-house.
Fund dynamics: regional VCs raising new funds pushed for realizations, driving proactive sale processes.
Sector-wise, CEE follows broader European patterns:
Business services and industrials lead in transaction volume.
Software and IT services are particularly attractive thanks to strong talent pools and digitisation trends.
Traditional sectors like automotive and construction remain active but face global trade and cost pressures
What does this mean for founders and investors active in CEE?
For founders, this means waiting for the “perfect moment” risks missing the buyer’s window. For investors, it underlines that CEE scale-ups are now proven exit stories, with buyers actively scanning the region. Preparation – in governance, metrics, and buyer relationships – will determine who captures premium multiples in the next wave.
Outlook for H2 2025: Optimism with cautiousness
Looking ahead to the second half of 2025, these are what we can expect:
Deal flow is expected to stay strong, particularly in tech, infrastructure and services.
More private equity funds may sell their portfolio companies in H2, as they look to return capital to investors and take advantage of active buyer interest
Regional consolidation and possible megadeals will likely remain part of the picture, even as many founders continue to wait for the “perfect timing” to sell.
Uncertainty remains, with tariffs, geopolitical risks and long-term rates still weighing on confidence. Yet, as PwC notes, “uncertainty may be the new constant”, and dealmakers who prepare strategically will outperform.
Summary
H1 2025 proved that European M&A is resilient, with deal flow at decade-high levels. For CEE, rising buy-side demand and steady valuations mean that both founders and investors have a real window of opportunity in H2. Let’s see at the end of the year how it turns out.
How Absolvo can support you in your M&A strategies?
At Absolvo, we know that preparation and the right partner can make or break a deal. Our experience shows that founders who prepare well in advance (often 2–3 years before a potential exit) and strategically position their business while accessing the right investors can achieve 2-3x better valuations and receive more competitive offers. With decades of M&A experience and a network of 28,600+ active investors, Absolvo help you navigate these times with confidence, because now may be the best time to act.
Reach out if you want to talk to us and prepare together for mastering your M&A strategy and exit opportunities.
Pattern #1: Private Equity Fuels Strategic Expansion in CEE Tech
PE-backed multi-strategy execution
Like in a recent deal, where Hg is supporting JTL in advancing its SaaS product development while also enabling the company to expand regionally and into adjacent sectors, PE investors’ arekeen to find good targets. The acquisition of Dealavo is a prime example of these strategic objectives in action, just like Revolution Software’s by Seyfor, backed by Sandberg Capital and many more. This pattern is increasingly visible across the region; among our clients we see many CEE-based companies being approached by private equity-backed buyers.
PE backing fuels acquisition-led expansion
Since securing investment from Hg in Q4 2023, JTL-Software has completed five acquisitions - a notable shift from its previous track record of zero deals. With Hg’s capital and strategic support, JTL is aggressively growing its capabilities, market reach, and competitive position. Since Exadel partnered with Sun Capital Partners, the company has executed multiple acquisitions across Bulgaria and Poland. These moves expand its delivery footprint and align with a broader strategy to scale rapidly through inorganic growth
Takeaway
When a private equity firm backs up your potential buyer, it may be the right time to consider a transaction with them. PE involvement often signals future consolidation, strategic add-ons, and regional platform-building. Growth pressure and financing is given. We are directly involved in such transactions, often negotiating with private equity firms on the other side of the table. We’ve seen cases when a PE-backed company executed 25+ deals in 1,5 years, that highlights the pace and intensity of buy-and-build strategies once the capital and mandate are in place.
JTL strengthened its cloud-native multichannel suite by acquiring Dealavo’s advanced pricing and market intelligence solutions. This enhances JTL’s value proposition to existing clients and supports upselling within its ecosystem.
AI capabilities as a differentiator
Anthill, acquired by Exadel, brings significant expertise in data, AI, and enterprise software development. These capabilities align with Exadel’s strategy to deliver innovation-focused,high-value digital services.
Strategic fit
These buyers are increasingly focused on acquiring companies that complement their core platforms. By integrating specialized capabilities like pricing automation, data engineering,or cloud-native tools, acquirers can quickly expand their value offering. Simple as that: the buyer can offer additional features, modules or software to their existing client base almost immediately and start generating revenue (and profit) from day one.
Pattern #3: International Expansion Through CEE Tech Hubs
Global expansion through local leaders
Dealavo’s presence across 30+ markets supports JTL’s regional expansion goals, especially in the DACH region.
Cross-border scale
Savangard, acquired by Digia, already generated nearly 30% of its revenue outside Poland, helping Digia diversify risk and broaden its reach across Europe.
CEE as a delivery hub
With the acquisition of Anthill, Exadel makes Bulgaria its second-largest European delivery location. Buyers increasingly recognize CEE’s importance for nearshoring, talent access, and strategic delivery capacity.
These deals can illustrate a larger trend: once acquirers become active in the CEE region, they are more likely to pursue follow-on acquisitions due to growing familiarity with the legal and business environment.
Pattern #4: Smart Valuations in CEE Tech M&A Deals
Attractive pricing dynamics
Digia’s acquisition of Savangard at approximately 6.5x EBITDA reflects a disciplined yet strategic approach. This valuation is below the 8-12x EBITDA median typically observed in the regional IT services space.
Takeaway
High-quality targets that demonstrate growth, profitability, unique capabilities, visionary management and international reach continue to attract strong valuations, especially when they fit into larger strategic narratives.
Pattern #5: Retaining Local Talent and Brands in Regional Deals
Preserving team and identity
Savangard will continue tooperate as a subsidiary under Digia, retaining its leadership and brand (a model that supports client trust and post-deal stability).
Gradual integration
Anthill will initially operate as “Anthill by Exadel,” signaling respect for the company’s culture and relationships while ensuring alignment with the parent company’s global operations over time.
Takeaway
As per our experience, more and more acquirers – particularly in tech and innovation-driven sectors – are shifting away from fully integrating acquired teams to preserve innovation, retain talent and reduce cultural friction. Research also supports this trend,highlighting that light-touch integration and portfolio models help maintain agility and morale while enabling faster realization of value. Forcing integration can undermine the very qualities that made the target company attractive in the first place.
Pattern #6: Rise of the vertical software integrators
A new type of buyer is becoming increasingly active in CEE: vertical software integrators. These firms typically focus on a specific or narrow set of industries, and their goal is to build platforms of industry-focused software and services that can scale internationally. As global economic uncertainty led many strategic buyers to become more cautious in recent years, these specialized players have grown bolder. From the UK to Dubai, and from Germany to Poland, we're seeing more of these integrators actively exploring the region, engaging in deals and establishing a broader presence in CEE. We’ve seen this trend firsthand. Our team recently closed two transactions involving vertical software integrators, and we’re tracking several more in the pipeline.
TheCentral and Eastern European technology M&A marketis clearly evolving. International buyers - both private equity-backed and strategic - are actively acquiring regional companies to access talent, specialized capabilities, IP, and scalable platforms.
Successful targets often exhibit a combination of international client exposure, cloud or AI-enabledservices, globally tested products, and a strong niche focus. As more capital flows into the region and acquirers grow increasingly comfortable with local dynamics, we anticipate continued momentum in the CEE deal market.
About Absolvo
Absolvo specializes in M&A and growth financing, backed by 180+ completed deals collectively in the Central and Eastern European region. We support technology companies through strategic exits, private equity transactions, and cross-border growth initiatives. If you are considering an exit or a strategic partnership, our team is ready to help you prepare and position your business toward an exit that could deliver 3–5x its fair value.
The CEE region has a total population of more than 130 million people – higher than the sum of DACH region and Sweden’s –, and accounts for approximately 30% of the European Union's total population of approx. 450 million. The region’s combined GDP was more than $2 trillion in 2023, close to Canada’s total ($2.24 trillion).
The economic progress of the CEE region is unmistakable. Countries such as Hungary, Czech Republic, Slovenia, and Poland have significantly improved their GDP per capita since 2018, steadily closing the gap with the EU average. This trend reflects broader economic development, increased purchasing power, and improving business conditions across the region.
IT Services Market Growth in the EU
Annual revenue growth in IT services in the next 5 years is expected to exceed the EU average in every major CEE country, that forecasts a strong and sustained digital boom.
2. A Thriving ICT sector with strong foundations
The ICT sector plays a central role in the region’s economic future. The CEE region is rapidly advancing as a digital hub, with countries like Croatia, Czechia, and Estonia exceeding the EU average. The increasing investments in digital infrastructure such as data centers and cloud services highlight infrastructural development while EU-backed initiatives alongside regional collaborations also underscore how regulatory frameworks drive growth in the region.
In some CEE countries like Bulgaria and Hungary, the value added by the ICT sector already exceeds the EU average. The region boasts a higher share of ICT employment and nearly double the number of ICT companies per 1,000 inhabitants, showcasing an increasingly vibrant tech ecosystem.
Value Added for the ICT Sector in the EU
Supporting this momentum is a deep pool of local talent, tech engineers ranked top performing based on various rankings. The proportion of ICT graduates across CEE countries consistently surpasses the EU average.
Romania leads the way, with over 6% of graduates specializing in ICT fields, a key factor in attracting tech investment and innovation.
ICT Graduates in the EU
Furthermore, labour costs remain significantly lower in CEE than in Western Europe. In 2024 the hourly labour costs across the region are often under €20, while IT salaries are more than 30-40% lower than in Western tech counterparts like Germany, the Netherlands or Luxembourg. For global tech firms, this combination of affordability and quality talent is hard to ignore.
Consequent to the recent Ukrainian-Russian war, the CEE tech pool is experiencing a large influx of IT talent relocating from Ukraine, which boasts one of the largest developer communities in Europe.
3. Global Players and CEE
Recently the CEE region has become a magnet for multinational corporations and global tech leaders, already drawn many multinational companies like Microsoft, Google, Intel, Oracle, and HP in the past to establish a strong presence here.
OpenAI CEO Sam Altman has publicly praised Poland’s engineering talent, calling it crucial to OpenAI’s success. OpenAI’s plans to open European headquarters in Poland signal growing confidence in the region’s innovation potential.
4. Tech sector: the heart of M&A activities in the region
The technology M&A sector plays a key role in the region, accounting for 15-25% of all completed deals in CEE and contributing 10-30% of the region's total deal value through the years. Western investors – especially from the US, Germany, and the UK – dominate inbound deal activity, drawn by strong fundamentals and a high return potential.
CEE startup exits have quadrupled over the past decade,
including Croatia’s Photomath acquired by Google, and Bulgaria’s Pliant bought by IBM.
In 2023, nearly 40% of funding came from outside the region, especially from Western Europe and North America, increased from 2021’s figure of 30%.
AI has become a key focus – 45% of all funding in 2023 was directed toward AI-related startups. Vertical sectors such as enterprise software, security, fintech, and robotics are among the most heavily funded.
M&A Volume and Deal Value Inbound to CEE by Sectors
UiPath’s Global success – a relevant example
Romania-based UiPath is a prime example of the CEE region’s tech potential. Founded in 2005, the company transformed from a small RPA startup into a global automation leader. Backed by early investment from CapitalG (Google’s venture arm), UiPath rapidly expanded, acquired multiple companies, and eventually launched a $1.3 billion IPO on the NYSE—one of the largest US software IPOs in history.
Today, UiPath serves clients in over 30 countries and employs more than 4,000 people globally, embodying the rise of CEE as a launchpad for world-class tech firms.
Conclusion
Central and Eastern Europe is not just an emerging player, but a rising future force in the global technology arena. The region combines fast-growing economies, digital readiness, abundant technical talent, low operational costs, and increasing investor confidence. With a supportive policy environment, strong startup activity, and a proven track record of scaling global tech successes, the CEE market is set to outpace much of Europe in digital transformation.
For companies, investors and entrepreneurs seeking high-growth opportunities, CEE stands out as one of the most promising frontiers in the global tech landscape.
Why Private Equity? Timing, Strategy, and Opportunity
Both companies entered the PE universe with different motivations, but a shared recognition that scaling sustainably required more than own capital available and organic growth.
For WTS Klient, the trigger was internal due to different visions. This divergence created a natural inflection point where bringing on an investor provided liquidity and strategic alignment.
In Finshape’s case, the PE partnership emerged during a moment of strategic ambition. After a management buyout, the team saw an opportunity to merge with a similar Czech-based company. This merger required immediate capital and the ability to execute a cross-border M&A—something only a capable PE partner could support.
In both cases, the decision wasn’t about a lack of ambition but about enabling the next phase of that ambition through structure, capital, and expertise.
What Changes When PE Enters the Room?
While financial resources were a clear value-add, both founders emphasized the operational transformation that comes with private equity investment. Reporting, strategic planning, and performance tracking became more formalized and more demanding.
“PE didn’t mean losing control - but it did mean more structure, more KPIs, and real accountability.”
said Jozsef Nyiri, referencing their use of the 'Rule of 40' to combine profit margins and growth rate to benchmark success.
For WTS Klient, it meant upgrading internal systems and introducing new layers of professional management to support a tripling in headcount over just a few years.
Tamas Gyanyi added that investor oversight brought more than just pressure – it brought professionalization.
“We became more efficient. We didn’t just grow in size—we grew up as an organization.”
he said.
Integration and Culture: Growth with a Human Lens
With private equity often comes consolidation—and with that, the challenge of integrating teams, processes, and cultures. Both WTS Klient and Finshape experienced this firsthand.
WTS executed multiple acquisitions in short succession. While this enabled rapid expansion, it also introduced high staff turnover in the acquired firms. Rather than see this as a setback, Gyanyi framed it as an opportunity to re-staff with future-oriented, culturally aligned professionals. The firm also launched an employee ownership program to retain top talent and strengthen internal alignment with long-term goals.
Finshape invested the time by face-to-face interactions and fostering mutual understanding, the firm gradually aligned its leadership culture.
In both companies, a central theme emerged: preserving core values amid scaling requires intentionality and communication. Social initiatives, direct engagement from top leaders, and open-door practices helped maintain a sense of unity even as operations expanded.
The Role of AI and Digitalization in Future Growth
As both companies look ahead, technology and AI are expected to play a larger role in driving efficiency and profitability. WTS Klient is already leveraging AI through its global network’s digital platform, which supports faster, semi-automated tax advisory responses. The firm also anticipates AI playing a bigger role in payroll and HR automation, reducing the need for manual roles and.
“We’re already using AI to semi-automate tax advisory. In payroll and HR, it’s going to help us scale and enhance EBITDA margins.”
said Tamas Gyanyi.
At Finshape, digitalization is embedded in the product, but operational AI initiatives – like measuring developer efficiency or improving test case throughput – are also becoming areas of focus. The investor’s support in bringing financial and analytical rigor is seen as a key enabler of such innovation.
“Even internally, we use AI to track developer efficiency or speed up test cycles—it’s becoming part of our operating rhythm.”
added Tamas Nyiri.
Balancing Investor Goals with Founder Vision
Despite the operational enhancements and strategic benefits, the founders acknowledged that conflict is sometimes part of the journey. Differences often arise in areas like sales strategy, where investor-level perspectives may not always align with on-the-ground realities. However, both founders expressed appreciation for the tension, as it often results in better outcomes when managed through transparency and mutual respect.
They also reflected on the personal growth required to operate in a PE-backed environment. Learning integration strategy, managing complexity, and accepting board-level scrutiny are all part of the evolution from founder to scale-up leader.
Crucially, both companies were able to retain their entrepreneurial spirit—not despite the investor, but often because of the structure and discipline the investor introduced.
“Sales is like football – everyone thinks they’re a coach.” Jozsef joked. “There were debates, but constructive ones. And we’re better for it.”
“I had to learn integration, HR, investor reporting – things I never planned for. But I’m a better leader now because of it.”
Tamas reflected.
Final Thoughts
The session concluded with a sense of measured optimism and maturity. For both WTS Klient and Finshape, the journey with private equity is not just about funding expansion, it's about scaling with intention, structure, and cultural integrity.
Private equity is often viewed through a transactional lens, but this panel made clear that it can be a deeply transformative partnership—one that helps companies not just grow faster but grow better.
As both founders continue executing their buy-and-build strategies, the lessons from this session reinforce a broader truth: when aligned with the right partner, private equity can be a powerful force for long-term, people-centric value creation.
The session opened with a macro-level view of the market. Following a period of inflated valuations and unpredictable fundraising conditions, investors now see stabilizing trends and greater clarity for deployment.
According to recent figures, the volume of CEE PE buyouts remained relatively stable compared to previous years, with approximately 150 deals executed, similar to 2022 and 2023. On the exit side, the number of PE-backed exits in the region saw a slight increase, which is a promising sign for liquidity. Although, deal values again fell, which aligns with global observations that valuations have normalized from the overheated levels of 2021 and early 2022.
CEE PE M&A buyouts and exits
Despite the challenging environment, several private equity firms remained highly active in the CEE region (including our guest, Abris Capital). This continued presence of leading firms underscores the long-term strategic commitment to the region, even in a cooling market.
The outlook among professionals remains cautiously optimistic. As noted in a supporting survey, 91% of respondents expect PE activity to increase in 2025, with strategies focusing on market consolidation and buy-and-build approaches. However, macroeconomic factors (such as geopolitical instability and slowed economic growth) are expected to weigh heavily on deal-making strategies in the near term.
Expected change in M&A transactions with PE involvement (2025 vs. 2024)
“There’s been a consolidation in valuations… targets are no longer overpriced, which is finally making room for deals again”
noted Tomasz Hajduk from Abris Capital.
Both firms confirmed from their own experience that there is a gradual reactivation in the market, in line with broader expectations. This creates a more favourable environment for executing deals, especially for funds already well-capitalized and experienced in CEE dynamics.
Platform Deals and the Buy-and-Build Model
A core focus for both Abris and Provectus remains the buy-and-build strategy, which they view as the most effective approach to value creation in fragmented sectors. Provectus has leveraged this model across several verticals, particularly healthcare, where they’ve built leading regional players through a series of add-ons.
Rather than passive acquisitions, the emphasis is on active operational development—professionalizing management, centralizing procurement, and investing in shared services. The result is not just revenue growth but the creation of platform companies that are structurally scalable and strategically differentiated.
“We focus on fragmented markets where you can consolidate smaller players into a dominant group – that’s where real value creation happens”
said Marko Galic, referencing Provectus Capital's success in healthcare.
Similarly, Abris employs buy-and-build as a foundational strategy, but also looking for transformational deals.
Their portfolio includes businesses that have undergone full-scale transformation. Not just geographic expansion but business model reinvention. This includes shifting traditional service companies toward digital, tech-enabled revenue models, which provides multiple levers for future growth and exit readiness.
Founders as Partners: Transition Planning Is Key
For PE firms, the acquired company’s team and management are key, and both firms approached the founders and management with a clear, structured process. Founders are typically retained to preserve institutional knowledge and ensure continuity. However, investors expect early conversations around succession planning and the professionalization of leadership.
Rather than abrupt changes, the model is built around gradual transition—starting with strategic hires such as CFOs and COOs who can prepare the business for its next phase of growth or eventual sale. The ability to manage this transition smoothly is seen as a key differentiator in the CEE context, where many companies are still founder-led and under-resourced in senior management.
VCs Turning to PE: A Growing Trend
One emerging dynamic in the region is the increasing number of VC-backed companies seeking exits through PE. As capital availability in venture markets contracts and IPO paths remain limited, many startups that have matured but not scaled explosively are looking to PE as the next logical step.
“We’ve had VC-backed firms approach us after growth slowed. We step in with majority control, operational expertise, and turn them into profitable add-ons.”
said Tomasz.
This is particularly true for companies that have strong fundamentals but need operational discipline and a route to profitability. PE firms see these as attractive add-on candidates or, in some cases, small platforms. While these opportunities require a mindset shift—from founder control to PE governance—they are becoming more frequent and viable as the ecosystem evolves.
ESG and AI: Practical Applications in Value Creation
Environmental, Social, and Governance (ESG) factors are no longer just compliance items, they are fully embedded in investment processes. Both firms conduct ESG due diligence on every deal and apply structured improvement targets post-acquisition. ESG performance is now directly tied to incentives and increasingly considered essential for any successful exit, especially when selling to Western strategic or financial buyers.
“Our portfolio companies report on ESG alongside financials and management bonuses are tied to those targets.”
said Marko.
On the AI front, investors are selectively integrating tools for market mapping, reporting automation, and portfolio company operations. While proprietary AI development remains limited, commercial tools with embedded AI capabilities are reducing manual workloads and improving operational efficiency. Use cases, such as content automation for e-commerce platforms, demonstrate how even small innovations can unlock significant productivity gains. At the same time, they made it clear that despite AI’s great potential, they won’t act like VCs. For them, early-stage deals are off the table, as their investment thesis and mandate remain firmly rooted in the private equity approach.
Closing Reflections
The session concluded on a grounded but positive note. Both Hajduk and Galic emphasized that while uncertainty remains a feature of today’s markets, it also creates opportunities for investors who stay disciplined, focused, and adaptable.
In their view, private equity in CEE is entering a new phase—one that favors strategic clarity over market timing, active value creation over financial engineering, and partnerships with entrepreneurs who are ready to evolve.
As 2025 unfolds, the message from leading investors is clear: with the right model, right sectors, and right relationships, CEE remains one of Europe’s most promising regions for private equity success.
Pattern #1: B2B niche targets are attractive for vertical software firms
Example to highlight:
Upliift, a London-based investor, focusing on European B2B software firms with revenues between €1-25 million acquired SRC, a Slovenian software development firm with over 200 employees and a presence across several countries in the CEE region.
Pattern explained:
This transaction aligns with a recent trends in the region, where a new class of investors such as Vesta Software Group, Everfield, saas.group, Jonas Software or Constellation (and many more) target cashflow-positive, founder-owned B2B software companies in niche markets. Unlike traditional strategic buyers, these investors prioritize maintaining the independence of acquired companies, fostering growth without full integration.
Pattern #2: Prior partnership with acquirer increases the chances of transaction success
Example to highlight:
The recent acquisition of Polish companies Mediarecovery and SafeSqr by Dutch firm DataExpert, which was rooted in over a decade of increasingly close cooperation between the two entities. DataExpert has employed a similar strategy in the past, collaborating with Swedish Forensic Experts Scandinavia AB before acquiring them in 2018.
Pattern explained:
When acquisitions stem from years of cooperation, buyers gain a deep understanding of the target's strengths, values, and potential revenue impact. This prior collaboration can also benefit the target by justifying a higher purchase price, often supported by proven results.
Pattern #3: Private Equity fuels inorganic growth
Example to highlight:
Software Mind, a Polish software development services provider, backed by Enterprise Investors – one of the largest Private Equity funds in Poland and the CEE region, acquired Gama Software, a software development company based in Romania.
Pattern explained:
The involvement of PE firms is a key driver of M&A activity in CEE. Companies backed by PE often pursue aggressive buy-and-build strategies to scale and expand. As a result, these companies tend to engage in more acquisitions than their non-PE-backed counterparts, as growth is a key expectation from private equity investors.
Pattern #4: Consolidation is the good old strategy for growth
Example to highlight:
Bianor Holding’s acquisition of Prime Holding and Digital Lights in Bulgaria demonstrates a strategic move to consolidate capabilities and strengthen competitive positioning in the industry.
Pattern explained:
Consolidation is a powerful strategy for everyone, in this case, for IT service providers in the CEE region seeking to compete on European and global stages. To effectively challenge larger players in other markets, these companies must increase their size by pooling resources and expertise, allowing for faster scaling. As some CEE firms strive to penetrate these larger markets, size and operational capacity become crucial factors for success.
Pattern #5: Timing can make or break a deal
Example to highlight:
Moj-eRačun, Croatia's leading provider of SaaS business tools, specializes in digitizing administrative tasks with its flagship product that offers e-invoicing and document management solutions. This product seamlessly integrates with over 400 ERP systems, providing a substantial competitive advantage as Croatia prepares for mandatory B2B invoicing set to be implemented in 2025.
Pattern explained:
Timing significantly impacts deal success, especially in markets preparing for regulatory shifts. This upcoming regulation is anticipated to drive demand, adding competitive value. The favourable timing and anticipated revenue growth contributed to a noteworthy valuation in the acquisition by Visma, a Norway-based software provider with an existing track record in the region.
Summary
From niche B2B acquisitions to strategic timing, these insights reveal the diverse approaches shaping tech M&A in the CEE region. Understanding these patterns can be crucial for investors and companies alike, as they navigate the unique dynamics of Central Eastern Europe’s evolving tech landscape.
At Absolvo Consulting, we are actively managing transactions for tech and innovation-driven companies across Central and Eastern Europe. Our daily interactions with strategic buyers and private equity firms give us unique insights into investor priorities, emerging investment trends and market dynamics. This helps us gain a precise understanding of investor needs and focus areas, so we can tailor our deal strategies for our client’s projects to meet these specific requirements.
Get in touch with us
The "newsletter-modal_component" element here is exactly the same as the "Newsletter modal" component, but it had to be unlinked so that the custom code of the form could be mapped to the Webflow CMS. This message won't be visible on the live site.
Request Information
We use cookies to improve user experience. By clicking "Allow all", you agree to our website's cookie use.
For more info, visit our
Cookie Policy.